What is the scope and industry significance of the Metal Valve Market?
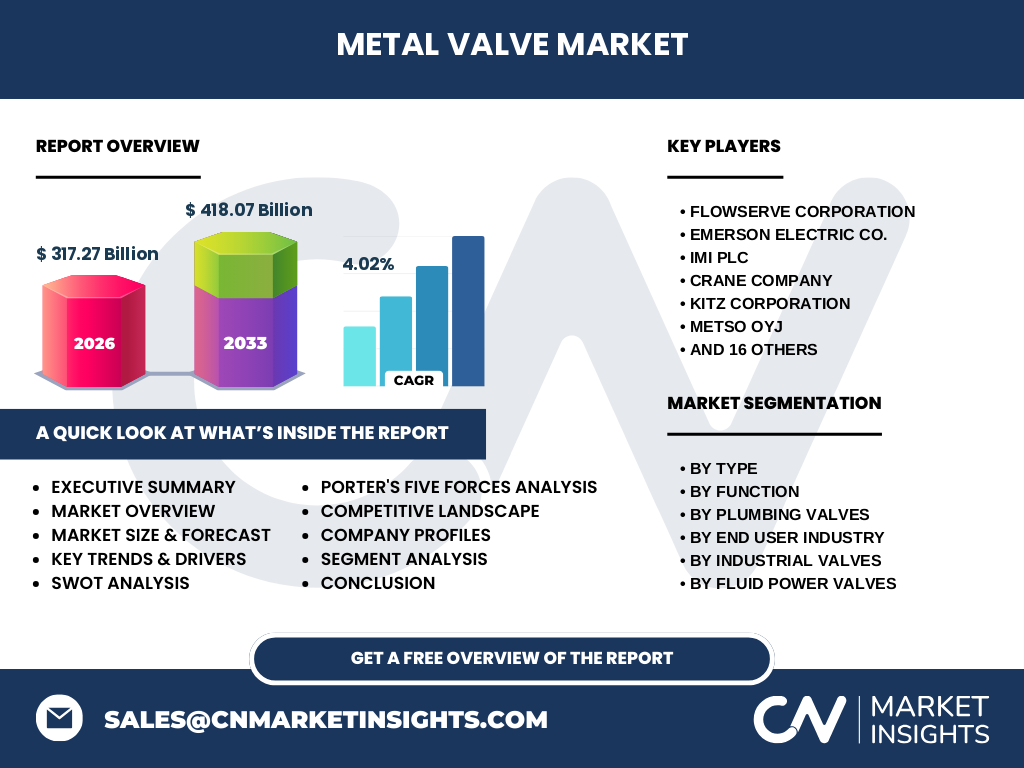
Our analysis indicates the Metal Valve Market is valued at 317.27 Billion in 2026, serving as the foundational infrastructure backbone for fluid management across global industrial complexes. This sector encompasses critical flow control devices utilized in volatile environments where elastomer seals fail, requiring robust metallurgical engineering to withstand extreme temperatures, pressures, and corrosive chemical agents.
Structural Growth Drivers and Market Restraints
Growth in the Metal Valve Market is propelled by aggressive expansions in petrochemical refining, deep-water extraction, and stringent environmental mandates enforced by bodies like the EPA. Conversely, market restraints include volatile raw material pricing for stainless steel and inconel, alongside tightening trade tariffs that disrupt traditional supply chain logistics centered around major Asian and European manufacturing hubs.
Emerging trends and growth patterns in the Metal Valve Market
The industry is witnessing a definitive pivot toward smart actuation and IoT-enabled diagnostic capabilities within heavy industrial environments. Digital transformation allows asset operators to monitor cycle counts and stem packing wear remotely, minimizing fugitive emissions and complying with ISO fugitive emission standards ahead of regulatory deadlines.
How did COVID-19 impact the Metal Valve Market and shape recovery?
The pandemic severely fractured global logistics networks, delaying capital expenditure projects across oil and gas and chemical processing plants. However, the post-pandemic recovery trajectory has accelerated automation investments, with facility operators prioritizing supply chain resilience and localized sourcing to mitigate future macroeconomic disruptions.
Competitive Benchmarking and Industry Concentration
The competitive landscape features a mix of multinational conglomerates and specialized severe-service specialists. Industry leaders like Flowserve Corporation, Emerson Electric Co., and IMI plc maintain dominant market share through proprietary alloy technologies, while agile niche players carve out high-margin dominance in cryogenic and slurry applications.
Executive Summary of the Metal Valve Market Overview
Our comprehensive research projects the Metal Valve Market to expand from 317.27 Billion in 2026 to reach 418.07 Billion by 2033, registering a steady 4.02% CAGR. This expansion is underpinned by resilient demand across energy, water treatment, and heavy manufacturing sectors seeking advanced metallurgical flow solutions.
Metal Valve Market Forecast (2027 to 2033)
Driven by a projected 4.02% CAGR, the market will scale from its 2026 baseline of 317.27 Billion to achieve a valuation of 418.07 Billion by 2033. This growth trajectory reflects sustained capital investments in emerging economies and mandatory retrofitting of aging industrial infrastructure to meet strict carbon-reduction targets.
Segmentation Analysis of the Metal Valve Market
The sector is intricately segmented by Type (Industrial Valves, Fluid Power Valves, Plumbing Valves, Specialty And Severe-Service Valves), Function (Control, Isolation, Pressure Relief, Non-Return, Flow Regulation), and End User Industry (Chemicals, Marine, Construction, Mining, Oil and Gas). Each category addresses specialized pressure-temperature ratings and fluid dynamic requirements.
Geographic Distribution and Regional Market Performance
Regional performance varies significantly, with North America and Europe leading in adoption of advanced automated control valves due to stringent environmental regulations. Meanwhile, Asia-Pacific remains the fastest-growing manufacturing epicenter, driven by rapid urbanization, massive chemical plant expansions, and expansive infrastructure investments across developing industrial zones.
In-Depth Regional Review of Manufacturing and End-Use Hubs
Asia-Pacific dominates volume consumption, anchored by heavy industrial output in China and India, where local suppliers like Neway Valve compete aggressively with global giants. Conversely, North American demand is heavily influenced by upstream shale oil extraction and replacement cycles in aging municipal water and wastewater treatment facilities.
Strategic Positioning of Leading Companies
Industry titans leverage distinct strategic positioning: Metso Oyj and Velan Inc. focus heavily on severe-service and cryogenic applications requiring exotic metal alloys. Simultaneously, firms like KITZ Corporation and Crane Company maintain broad portfolios optimized for high-volume commercial plumbing and standard industrial fluid control.
Porter's Five Forces Analysis of the Industrial Flow Sector
The threat of new entrants remains low due to high capital expenditure requirements for foundry tooling, severe-service testing certifications, and strict quality accreditations like API and ASME. Supplier power is moderate, balanced by the specialized nature of nickel-alloy and titanium sourcing required for extreme corrosive environments.
SWOT Analysis: Strengths, Weaknesses, Opportunities, and Threats
Key strengths include unmatched durability in extreme environments, while weaknesses stem from high initial capital costs compared to polymer alternatives. Major opportunities lie in green hydrogen infrastructure and carbon capture systems, whereas threats involve macroeconomic currency fluctuations and geopolitical trade barriers impacting raw material imports.
Value Chain Analysis from Raw Metallurgy to End-User Deployment
The value chain begins with raw material foundries supplying stainless steel, carbon steel, and exotic alloy billets. Precision machining, assembly, and hydrostatic testing form the core manufacturing tier, followed by specialized distribution networks that supply engineered valves directly to EPC contractors and plant operators.
Investment Insights and High-Potential Growth Pockets
Investors should target manufacturers specializing in cryogenic and corrosion-resistant metal valves tailored for green energy applications, such as liquid hydrogen transport and geothermal power generation. Companies possessing proprietary metal-seated technology are exceptionally well-positioned to capture high-margin retrofit contracts in traditional refineries.
Conclusion and Strategic Takeaways for Industry Stakeholders
Reaching 418.07 Billion by 2033 at a 4.02% CAGR, the Metal Valve Market rewards innovation in material science and smart actuation. Stakeholders must prioritize sustainability, low fugitive emission designs, and agile supply chain strategies to outmaneuver macroeconomic volatility and capture expanding industrial demand.
Research Methodology and Baseline Triangulation
Our baseline estimates are rigorously triangulated by cross-referencing trade registry data, primary executive interviews with chief engineering officers, and secondary macroeconomic indicators from global manufacturing indices. Bottom-up revenue aggregation from key market players ensures high data fidelity across all sub-segments.
Scope of the Report and Analytical Parameters
This report covers global market dynamics for metal valves from 2026 through 2033, providing quantitative sizing and qualitative insights across specified industrial, fluid power, and specialty categories. Regional exclusions and specific military-grade ordnance valves fall outside the primary commercial scope of this analysis.
Recent Developments, Strategic Partnerships, and M&A Activity
Recent industry momentum is defined by strategic acquisitions and technological alliances aimed at expanding severe-service portfolios. Key players like Spirax-Sarco Engineering plc and Parker-Hannifin Corporation have pursued targeted acquisitions to integrate advanced digital sensing capabilities directly into heavy-duty industrial valve bodies.